
Relocation & Mobility
When Two Real Estate Transactions Have to Work Together
A relocation often means a sale and a purchase whose timelines, contingencies, and closing dates depend on each other. Understand the coordination challenges — and where a single delay can affect the entire move.
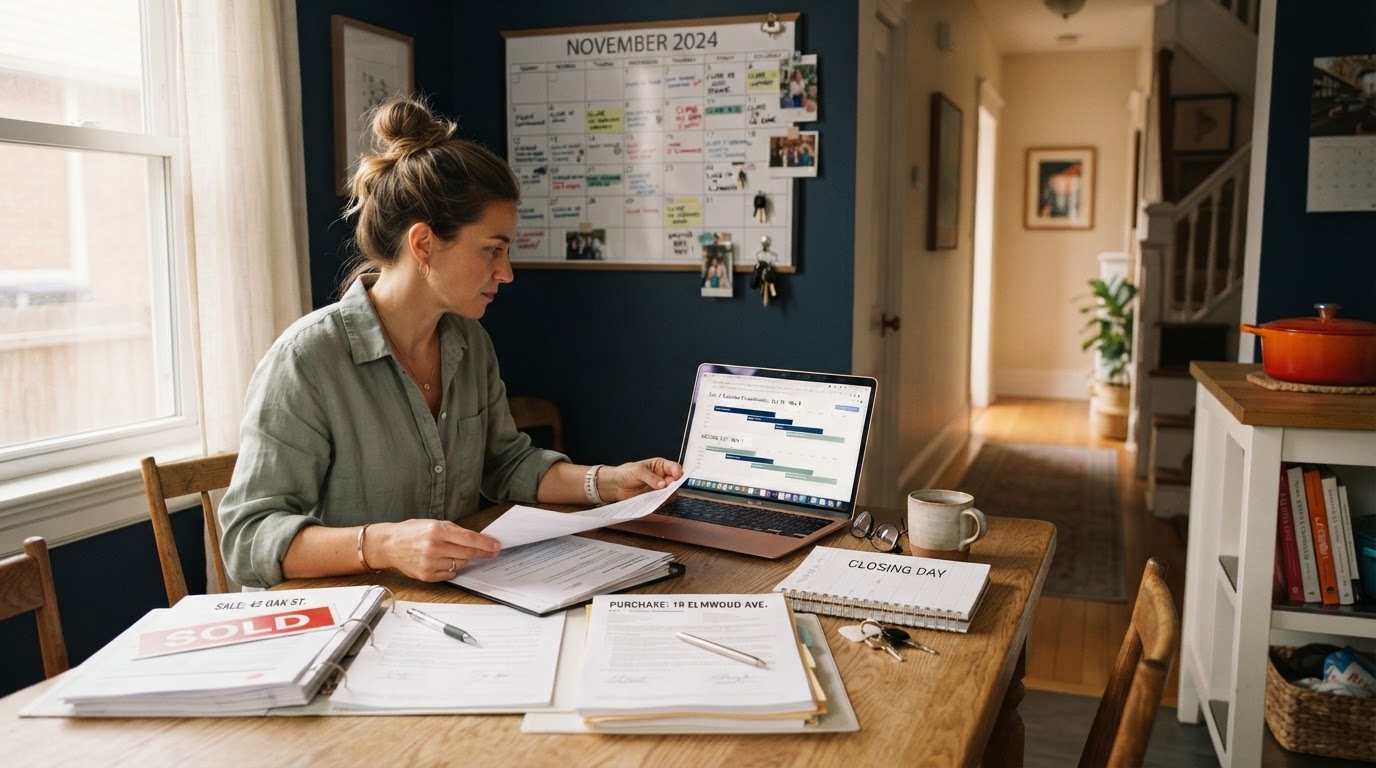
A relocation that involves selling one home and buying another is, in practice, two real estate transactions that have to fit together. Each has its own contract, its own inspections, its own appraisal, its own financing, and its own closing date. When the household needs the proceeds from the sale to fund the purchase — or needs the timing of the two to align so they aren't carrying two homes or left without one — the transactions become interdependent. The success of the move depends not on either one alone but on how the two fit together, and that coordination is where the most consequential delays and decisions tend to arise.
Two timelines, one move
Each transaction runs on its own clock. The sale of the departure home depends on finding a buyer, reaching an agreement, clearing contingencies, and closing. The purchase of the destination home depends on finding the right property, reaching an agreement, securing financing, clearing its own contingencies, and closing. When both have to happen in the same window — so the household can sell, move, and buy without a long gap or an extended overlap — the two clocks have to stay within reach of each other. They don't have to close on the same day. But they do have to close in a sequence and a timeframe the household can actually manage.
Where one delay becomes a larger problem
The challenge is that each transaction has its own points of friction, and a delay on either side cascades into the other. A buyer's financing falls through on the departure sale, and the household can't close on the destination purchase that was contingent on those proceeds. An appraisal comes in low on the destination home, and the financing has to be reworked, which pushes the closing, which extends the carrying period on the departure home. An inspection surfaces a repair, and the negotiation that follows delays a timeline that was already tight. None of these is unusual in isolation. What makes them consequential is the interdependency: when one transaction slips, the other is affected, and the household is the one standing in the middle of both.
“Two transactions don't double the complexity. They connect it — and a delay on one side reaches the other.”
Contingencies and the safety net they create
Contingencies are the mechanism that connects the two transactions and, used well, the safety net that protects a household from being committed to one while the other falls apart. A home-sale contingency on a purchase offer means the household isn't bound to buy the destination home unless their departure home sells. A financing contingency means neither transaction is final until the lender confirms the loan. These contingencies exist for a reason — they keep a household from being obligated to two transactions when only one is ready to close — but they also create dependencies, and in a competitive market, a contingency can make a purchase offer less attractive to a seller. The tradeoff between protection and competitiveness is a real one, and it deserves to be made deliberately, with the full picture of what each contingency protects and what it costs.
Closing dates and the logistics between them
Even when both transactions are on track, the logistics between the two closings matter. The possession date on the departure sale — when the household has to be out — and the possession date on the destination purchase — when they can move in — have to leave a workable window for the physical move. If the departure closing requires the household to be out before the destination home is available, temporary housing enters the picture. If the destination closing happens first, overlap and carrying costs do. The ideal is a sequence where the two closings and the possession dates leave the household with a clear, manageable path from one home to the other — and the realistic plan is one that accounts for what happens when that sequence doesn't hold.
Questions worth asking
- How do the timelines of the sale and the purchase actually relate, and what happens to one if the other is delayed?
- Which contingencies protect the household, and which make an offer less competitive in the destination market?
- What is the backup plan if the departure sale closes late — temporary housing, an extended overlap, or a renegotiated purchase timeline?
- How do the two closing dates and possession dates leave room for the physical move itself?
- Who is coordinating the two transactions, and are the professionals on each side communicating with each other?
This article provides general educational information, not individualized real estate, financial, or legal advice. Transaction coordination and contingency decisions should be evaluated with appropriately qualified professionals based on individual circumstances and local market conditions.
Related paths
These Jumpcity capabilities may be relevant to this situation.
AI tools were used in preparing this article. Jumpcity is responsible for its published content.
Continue exploring
Guides & Tools for Your Next Step.
Explore practical resources to understand your options, compare tradeoffs, and prepare for what comes next.
Move Sequence Comparison
Compare buying before selling, selling before buying, or coordinating both closings — cash required before the sale, overlapping housing exposure, temporary housing, and timing tradeoffs.
Compare my move sequenceMove Timeline Builder
Generate a suggested planning sequence back from a target move date you choose.
Build Your TimelineOverlapping Housing Costs Estimator
Estimate what carrying two homes could cost during an overlap, across a few durations.
Explore the EstimateThe Two-Mortgage Guide
Understand what it means to carry two homes at once — in plain language, with the right questions to ask.
Read the GuideRelated insights
Why Owning Two Homes Can Complicate a Relocation
Buying your next home before selling your current one can create overlapping payments, financial uncertainty, and unexpected timing pressure. Understand how these connected obligations shape relocation decisions — and what to weigh before taking them on.
When a Delayed Home Sale Changes the Entire Moving Plan
When the departure home takes longer to sell than expected, the delay reaches every part of the relocation — the financing, the timeline, the carrying costs, and the household's cash flow. Understand how one delay cascades and what to plan for.
Should You Sell Your Current Home Before Buying the Next One?
Selling first can reduce financial exposure and strengthen a purchase offer. It can also mean temporary housing, storage, and moving twice. Explore the tradeoffs before choosing an order for your move.
Useful context is worth sharing.
Not sure which path fits your situation?
What Happens After You Start
You share your situation. Complete the assessment — about three minutes, no obligation.
A person reviews it. Someone at Jumpcity reads what you shared to understand your goals.
We follow up with context. We reach out with relevant options and an appropriate next step.
A short, guided assessment · No obligation
A Path for Every Move.