
Relocation & Mobility
Moving Between Texas and North Carolina: What Homeowners Should Understand
Relocating between Texas and North Carolina involves two different housing markets, property-tax structures, insurance environments, and lifestyle costs. Understand the property decisions a move between these states creates — in both directions.
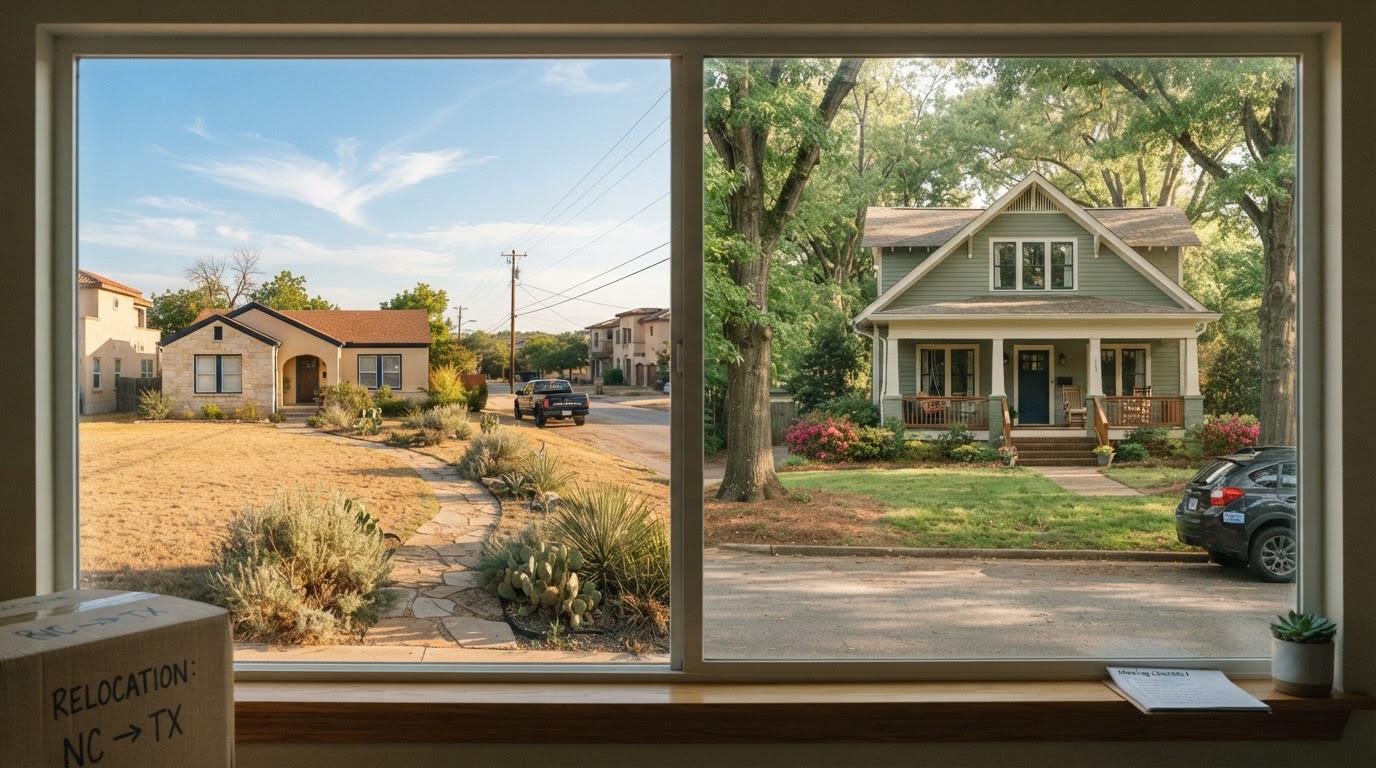
A move between Texas and North Carolina is, for many households, the kind of relocation that looks straightforward on a map and more complicated up close. The two states share enough — a relatively lower-cost reputation compared with some coastal markets, growing employment corridors, a strong draw for relocating families and retirees — that the move can feel like a lateral one. But the housing markets, the tax structures, the insurance environments, and the day-to-day cost of living are different in ways that matter to a property decision. Understanding those differences, in both directions, is what turns a cross-state move from a surprise into a plan.
Two housing markets, two sets of conditions
The first thing to understand is that there is no single Texas housing market and no single North Carolina housing market. Each is a collection of very different metropolitan areas — with their own inventory, price levels, pace of sales, and buyer competition — and those conditions differ further at the neighborhood and price-tier level. A household leaving a fast-moving Texas metro for a North Carolina one, or the reverse, should not assume the conditions they know in one market describe the other. The realistic timeline for selling, the negotiating room on a purchase, and the price a comparable home commands are all local, and they deserve to be evaluated with current, market-specific data rather than a statewide average.
Property taxes and the cost structure that differs
Property taxes are one of the more visible differences. Texas is broadly known for higher property-tax rates; North Carolina's are broadly lower — but the comparison is more nuanced than a single rate. What a household actually pays depends on the local jurisdiction's assessment practices, the applicable rate, and, in North Carolina, homestead or other exemptions that may apply. A lower property-tax rate on a more expensive home can produce a higher bill; a higher rate on a more modest one can be manageable. Neither state is universally cheaper or more expensive. What matters is the household's actual tax obligation in the specific destination jurisdiction, evaluated with current, verified local figures and, where the household's circumstances warrant it, a qualified tax professional.
Insurance and the regional risk picture
Homeowners insurance differs between the two states in ways that go beyond price. Texas and North Carolina face different regional risks — severe weather exposure, flood considerations, and, in some areas, insurance availability itself — and these affect what coverage costs and what it requires. A household moving from one state to the other may find that the coverage they carried no longer applies, that certain perils are treated differently, or that the cost or availability of a policy in the destination is not what they assumed. As with taxes, this is not a reason to avoid a move. It is a factor to understand, with a local insurance professional, before the household commits to a purchase in the destination market.
Employment, lifestyle, and the why behind the move
The reasons households move between these two states are usually a mix of employment, family, retirement, and lifestyle. Texas and North Carolina both have substantial employment corridors that draw relocating workers, and both have regions that attract retirees and second-home buyers. The property decision is shaped by that 'why': a household moving for a specific job may have a start date and relocation benefits that anchor the timeline; a household moving for retirement may have more flexibility but a different set of priorities around cost, access, and community. In both cases, the property decision and the life decision are worth planning together, and the right path in one state may not be the right path in the other.
Selling in one, buying or renting in the other
The mechanics of the move also depend on what the household does with the departure home and how they land in the destination. Selling a Texas home and buying in North Carolina — or the reverse — is two transactions in two markets, often with different professionals, different timelines, and different conditions. Some households sell and rent at the destination first, to learn the local market before committing to a purchase; others buy before selling to secure a home in a tighter destination market. Each path has its own tradeoffs, and the right one depends on the household's finances, the two markets' conditions, and the timeline the move allows. There is no single right sequence for a Texas–North Carolina move, and the choice deserves to be made with the full picture rather than a default assumption.
Why local, market-specific guidance matters
Because the conditions differ by metro, by neighborhood, and by price tier — and because the tax, insurance, and financing considerations are jurisdiction-specific — a move between these two states is one where market-specific professional guidance genuinely changes the outcome. A real estate professional who knows the destination market, a lender who understands how the household qualifies for the next purchase, an insurance agent who knows the local risk picture, and, where relevant, a tax advisor who understands the household's position across state lines — these are the people whose guidance turns a cross-state move from a series of assumptions into a coordinated plan. The value is not in one of them; it is in seeing the move as one transition with several connected parts.
Questions worth asking
- How do the housing-market conditions — inventory, pricing, pace, competition — actually differ between the specific metro you're leaving and the one you're moving to, right now?
- What will the property-tax obligation be in the specific destination jurisdiction, and how does that compare with the current one — after any exemptions?
- What does homeowners insurance cost and require in the destination, and how do the regional risk considerations differ from where you're leaving?
- Is the move driven by a job with a timeline and relocation benefits, by retirement, or by family — and how does that shape the sequence of selling, buying, or renting?
- Which local professionals — real estate, lending, insurance, tax — does the household need on each side, and how will the two sides be coordinated?
This article provides general educational information, not individualized legal, tax, financial, insurance, or real estate advice. State-specific tax, insurance, and regulatory matters should be evaluated with appropriately qualified professionals in the relevant Texas or North Carolina jurisdictions based on individual circumstances and current data.
Related paths
These Jumpcity capabilities may be relevant to this situation.
AI tools were used in preparing this article. Jumpcity is responsible for its published content.
Continue exploring
Guides & Tools for Your Next Step.
Explore practical resources to understand your options, compare tradeoffs, and prepare for what comes next.
Planning a Move Between States
Understand how your current home, next home, financing, and timing connect when a move crosses state lines — and how to approach the decisions without assuming a sale or a sequence.
Read the GuideMove Timeline Builder
Generate a suggested planning sequence back from a target move date you choose.
Build Your TimelineWhat Will Your Move Really Cost?
Account for movers, packing, storage, travel, setup, and contingency in one budget.
Read the GuideTotal Move Budget Estimator
Estimate movers, packing, storage, travel, temporary housing, and setup costs. Add a contingency to understand your total moving budget.
Estimate Moving CostsRelated insights
Why Moving to Another State Is More Than a Change of Address
Moving between states introduces different housing markets, tax systems, insurance costs, and lifestyle considerations. Understand the property decisions an interstate relocation creates — and what to weigh before choosing where to land.
When the Destination Market Moves Differently From the Market You're Leaving
A relocation means selling in one market and buying in another — and the two may be moving in opposite directions. Understand how different inventory, competition, and pricing on either side of the move create different strategic challenges.
Why the Cost of Living Can Change the Meaning of a Relocation Offer
A higher salary doesn't guarantee a better financial outcome if the destination's housing, taxes, and daily costs are higher too. Understand how to evaluate a relocation offer against the cost of living — not just the income.
Useful context is worth sharing.
Not sure which path fits your situation?
What Happens After You Start
You share your situation. Complete the assessment — about three minutes, no obligation.
A person reviews it. Someone at Jumpcity reads what you shared to understand your goals.
We follow up with context. We reach out with relevant options and an appropriate next step.
A short, guided assessment · No obligation
A Path for Every Move.